CT600 box 45: claim or relief affecting an earlier period
Short version. Claim or relief affecting an earlier period marks CT600 box 45 when a claim reduces tax for an earlier period. For a trading loss carry-back, enter the amount in Trading loss carried back. That makes the claim in the loss-period computation and ticks box 45 automatically. A manual box 45 tick alone does not make a loss claim.
Go to the steps and entry details
On this page
CT600 box 45Original or amended returnOne or two CT600sWhere you see it: Financial Data
Claim or relief affecting an earlier period marks CT600 box 45 when a claim reduces tax for an earlier period.
- The claim is filed with the return for the period in which the loss arose. It does not amend the earlier return or calculate its repayment.
- You supply the amount to carry back. HMRC applies it to earlier profits and adjusts the earlier tax.
- Clearing the amount restores your own box 45 answer. An unticked manual answer is kept while the positive amount ticks the box automatically.
When box 45 applies
Use it if all of these are true
- You are making a claim that reduces Corporation Tax for an earlier period.
- For trading loss carry-back, you have calculated the unused loss after current-period relief and the amount available against the preceding 12 months.
Do not use it if
- You only want to use losses brought forward in this return.Use instead: Trading losses and box 285
- You need the three-year terminal loss extension.Use instead: Terminal loss claims
The same trade must have been carried on in the earlier accounting period. Section 37 excludes a trade carried on wholly outside the UK. Earlier profits and other restrictions affect the claim. Read the complete section 37 conditions when preparing your amount.
A tick alone is not the claim
Both versions below have the same current-period Corporation Tax. Only the version with an amount makes a carry-back claim and reduces the loss carried forward.
Only box 45 ticked
- Trading loss carried back
- £0
- Loss carried forward
- £21,000
- Current-period Corporation Tax
- £0
Carry-back amount entered
- Trading loss carried back
- £15,000
- Loss carried forward
- £6,000
- Current-period Corporation Tax
- £0
Fictional example
- Company
- Willow Lantern Ltd
- Accounts period
- 1 April 2025 to 31 March 2026
- Prepared trading loss
- £24,000
- Interest receivable
- £3,000
- Customer-calculated carry-back
- £15,000
The company and all figures on this page are fictional.
Before you start
- Your prepared figures
- Trading profit or loss after the usual tax adjustments, and any other profits for this return.
- Your claim amount
- The unused loss you want to carry back, within the eligible earlier profits. This is your calculation.
- If amending
- Open the return for the loss period, not the earlier period that will receive the relief.
The company and all figures on this page are fictional.
Step by step
Company Profile & Period
- Accounting period
- 1 April 2025 to 31 March 2026
- What are you filing?
- HMRC CT600
- Trading status
- Active
- What the company does
- Trading
Complete the other choices and click Next →.
Financial Data
- Previous year
- Your prior-year figures, or 0 where a line had no amount. Not shown for first accounts.
- Turnover
- 0
- Cost of raw materials and consumables
- 0
- Staff costs
- 0
- Other charges
- 24000
- + Show all Profit & Loss options
- Open the additional profit and loss fields.
- Interest receivable and similar income
- 3000
- Balance sheet
- Your prepared balance sheet at the end of the accounts period
- Average number of employees
- Your average number, or 0
- Tax adjustments
- Open this section after entering your prepared figures.
- Trading loss carried back
- 15000Shown when there is unused trading loss, or when an amount is already entered. Blank or 0 means no carry-back claim.
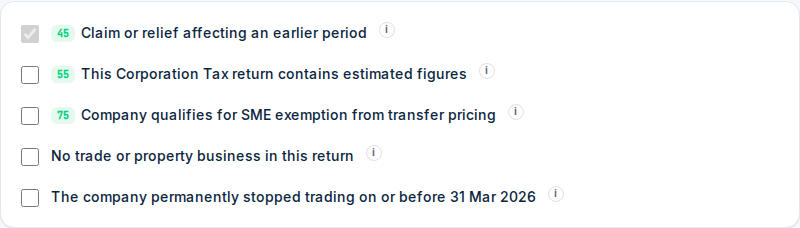
- Claim or relief affecting an earlier period
- Ticked automaticallyThe control is in Other return details, below the employees section and before This Corporation Tax return contains estimated figures. A positive carry-back amount locks the automatic tick.
Review & file
Corporation tax due£0 .00On taxable total profits of £0 at 0.0% · small profits- Review the claim
- Preview your documents (free) shows box 45 and the claim statement. Check the amount and loss-period dates.
For an existing filing, use Amend a CT600 filed with us to amend the loss-period return. A change only to this claim is an HMRC amendment. It does not resend Companies House accounts.
Two CT600 returns
When the accounts period ends more than 12 months after it starts, even by one day, each CT600 has its own amount and box 45 answer. Enter the claim under the dates of the return in which the loss arose. We do not allocate it by days. In separate-figures mode, enter it on the applicable CT600 tab.
A claim on return 2 does not reduce the tax shown for return 1. HMRC gives effect to that claim after processing it. For a mixed CASC with only one taxable return, only that return has these controls. Fully exempt returns have neither a carry-back claim nor box 45.
Check the documents
Check an X in box 45 of the relevant CT600 form PDF and the same amount in the claim statement and loss summary. Box 780 still reports the loss arising. A manual tick without an amount does not add a trading loss claim statement.
Related guides
Open the guide for the option that matches your filings.
Looking for a different field or step? See all filing wizard guides →
Official sources
More help:
Whether this route matches your filings is for you to decide, yourself or with your accountant.
Example companies and figures are fictional. Field names match the filing wizard as of 16 October 2026.